In October I went to a funeral of a former teacher of mine, who died aged 97. It had me reflecting that I haven’t been to that many funerals – more than 10 but fewer than 20 I’d say – and none of anybody who made it that long. He had not much family and the care home he lived his last few months in had very little to go on. I don’t know whether there were a dozen or so broker accounts to unravel…..
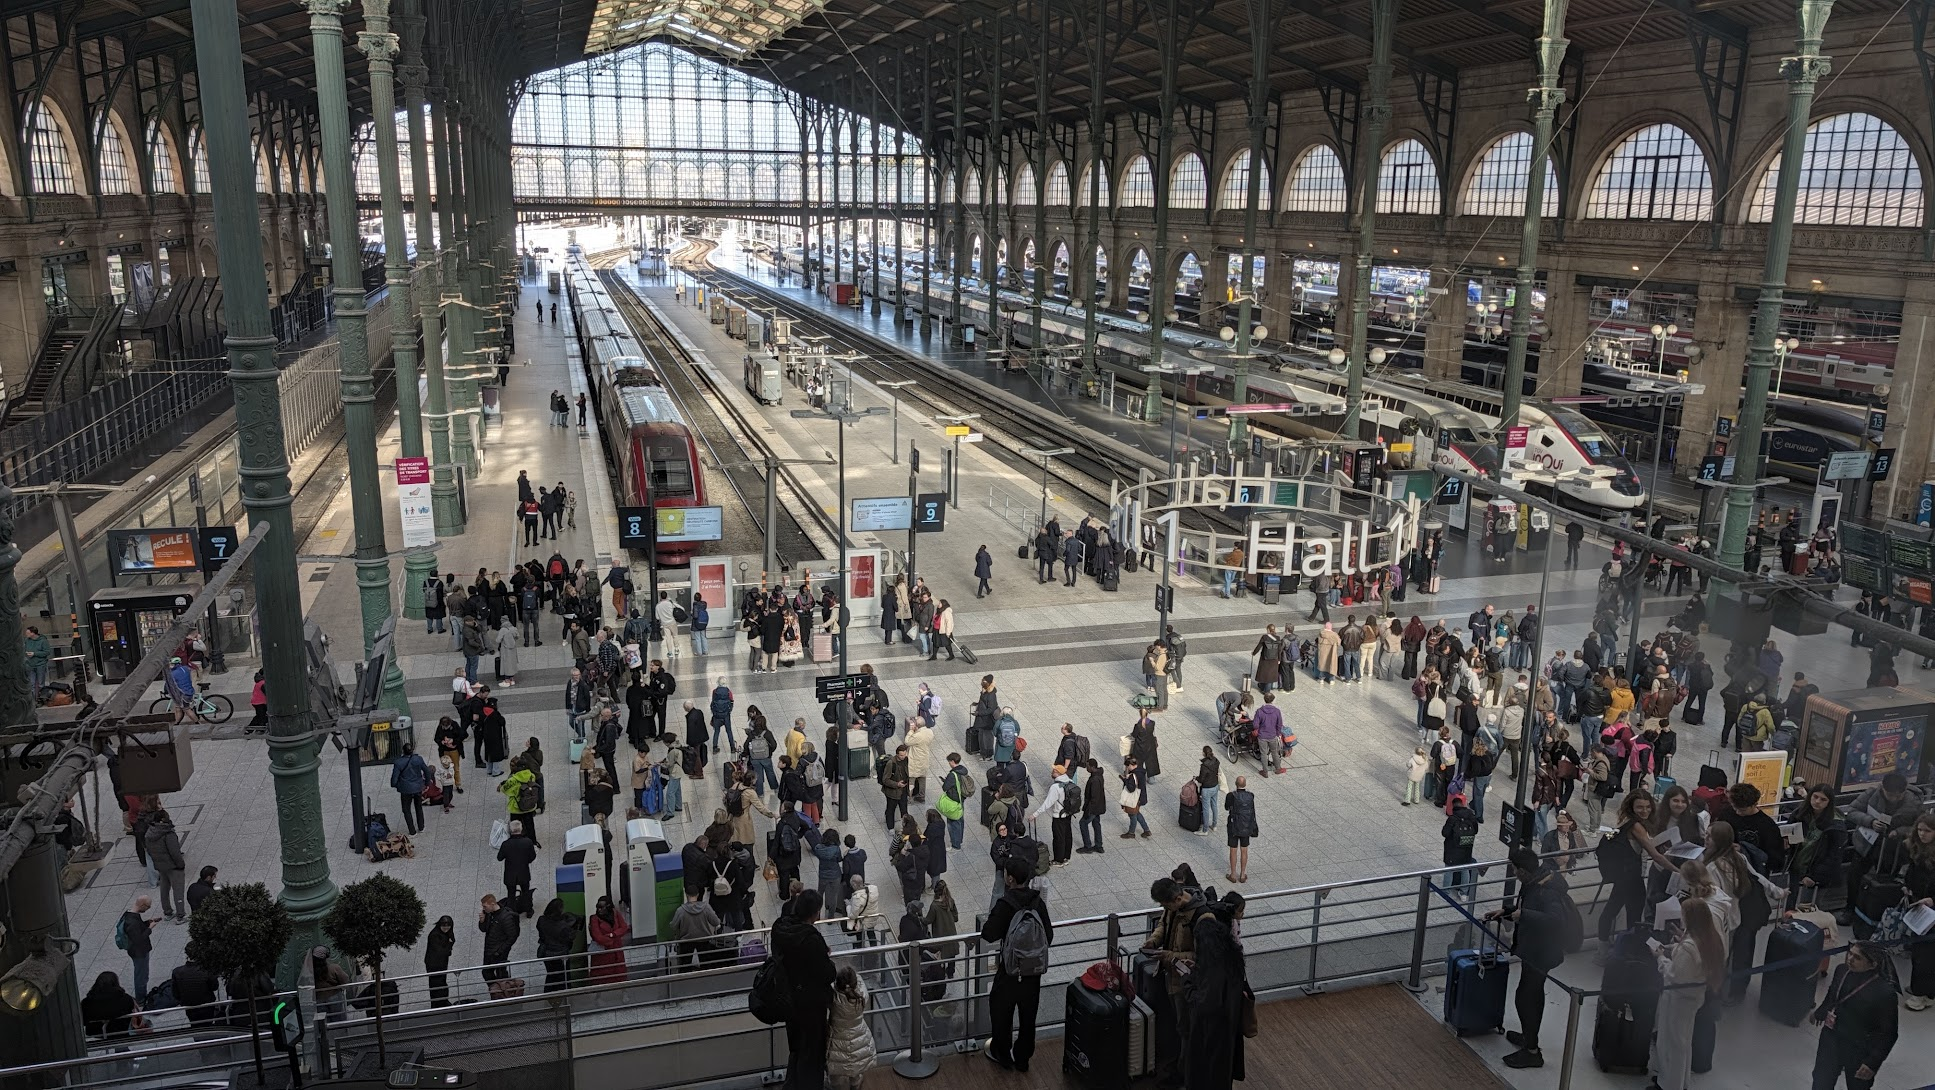
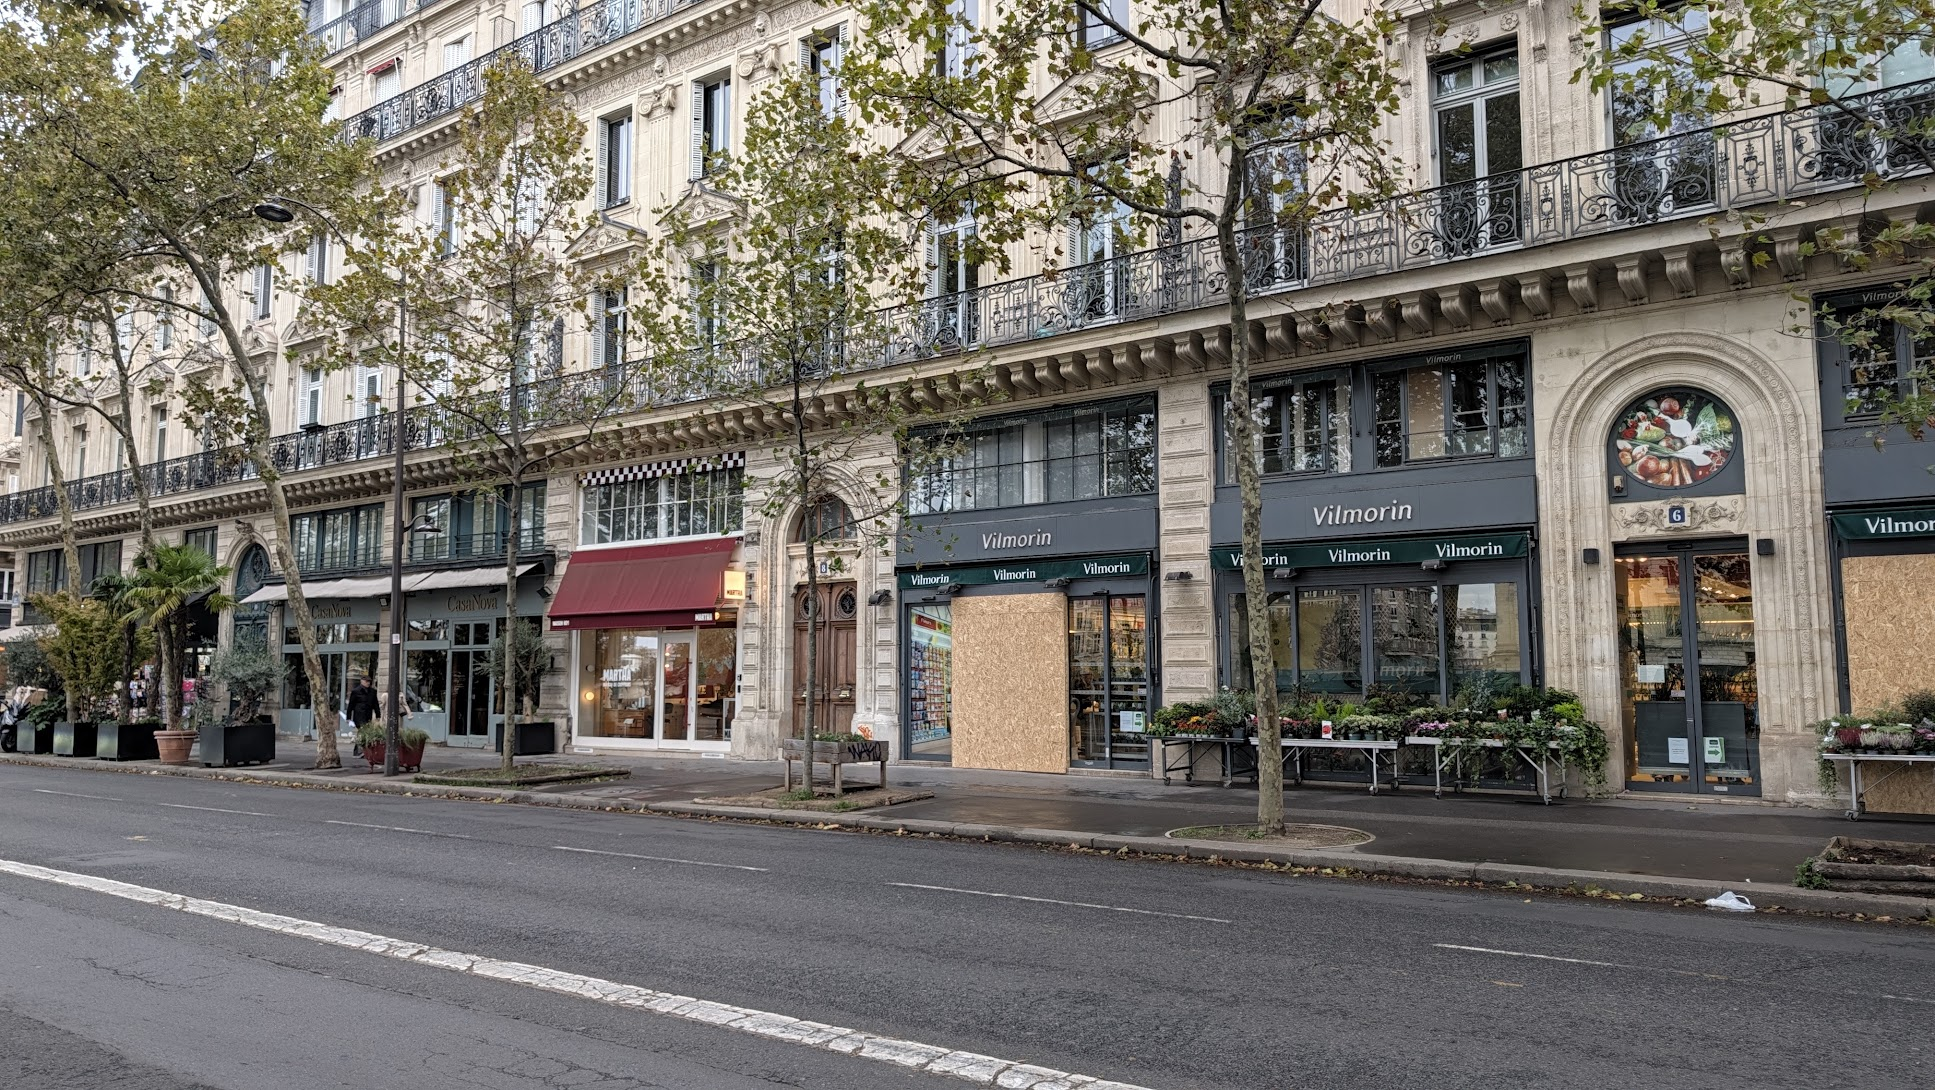
I also did some travel in October. To Paris and to Sri Lanka. I was in Paris during some of the long-running riots; they didn’t disturb me, but the sight of so many shops boarded up in St Germain was sobering.
I had a lovely safari trip to Sri Lanka. Forgive me for not sharing all my holiday snaps, but a couple are below.
Meanwhile, the UK news cycle felt like downstream backwash from the annual party conferences at the end of September. New PM Andy Burnham made some, to my mind, adroit steps – suggesting a reform of the pension triple lock which makes a lot of sense, and trying to move the Overton window around the UK / EU relationship. Co-incidentally, the UK economy stats are actually reasonably encouraging – and would be more so if it weren’t for the oil price spike caused by the USA’s attacks on Iran.
The biggest story in October, from a UK investor’s point of view, was supposed to be the UK budget. In fact it proved to be something of a ‘nothingburger’ – at least if you aren’t a private landlord (who have had their we-don’t-like-you tax hike raised from 2% to 4%) – which I think must count as Good News, given the Labour leftwing agitation for higher capital gains rates, wealth taxes, more mansion taxes etc.
Market movements in October 2026
What I said on Blue Sky about the October markets feels about right: AI-driven declines (notably in Asia/Pac) saw money rotate into bonds; UK ‘safety first (except banks)’ budget helped GBP and all UK assets (except banks). Rates heading upwards, following oil prices.
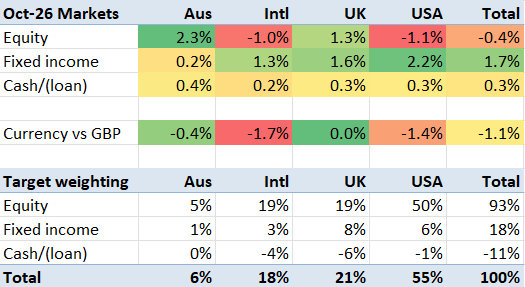
On a constant currency basis, markets dipped only very slightly (0.15%). The pound strengthened. Allowing for that, my benchmark markets dropped 1.3%.
My portfolio
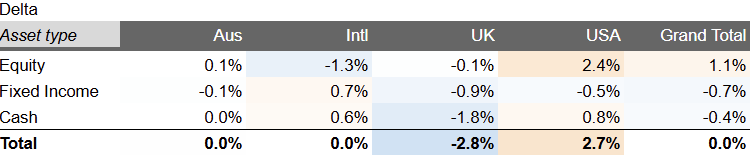
My portfolio dropped rather more than my benchmark – it dropped 2.3%. Harumph. This leaves me at the end of October up only about 3% on the year to date. There is still quite a bit to play for but the year isn’t turning out very well.
I remain a bit overweight on USA equities, and with the Asian stocks down materially I am now underweight International equities.
Income in October was a muted affair – less than a third of my end-of-Quarter September harvest. All in all, a mildly disappointing month for the portfolio, but a relief from the UK’s annual Budget.
Appendix: Press clippings