April 2017: elections & returns

I returned to London from my Easter break to the surprise announcement that Theresa May has called a general election on June 8th.  Normally I love elections and am a news junkie about them. Personally I think the PM has missed an opportunity to lance the Scottish nationalist boil by calling a simultaneous #indyref2.  So instead of that excitement, I find myself agreeing with piece in The Sunday Times today arguing that for once a foreign election, in France, is more exciting than the anticipated Tory landslide in the UK’s general election in June.

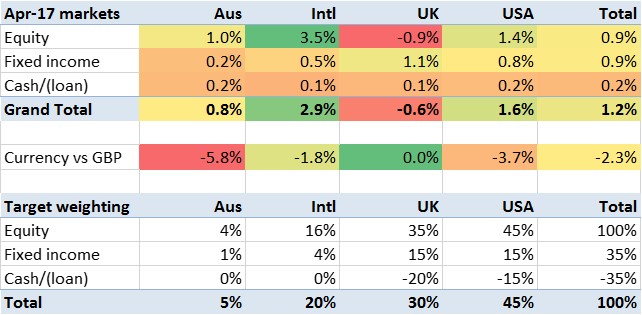
Certainly Macron’s win in the first round of the French election lifted European stocks considerably. The European index I use as my proxy for ‘international (i.e. non UK/US/Oz) equities’ rose 3.5% in April, well ahead of the English-speaking stock markets.  While we can’t ignore the prospect of a Le Pen win, it doesn’t appear likely from opinion polls. Much as people are knocking pollsters right now the only result they got wildly wrong in the last few years was the 2015 UK General Election result (where First Past the Post makes predictions particularly tricky). So most likely European markets are going to get better rather than worse.
2017 04 returns by asset type.jpg

The other big news in the markets for Brits was the jump in the pound, attributed to the prospect of ‘stronger and stabler’ UK leadership post the general election. Forex markets clearly haven’t clocked that the European leaders who do best in EU negotiations are those with credible domestic oppositions to appease, not those with autocratic majorities. In any case, the pound is still below $1.30 so the Brexit Brainfart hasn’t blown away yet.  But the pound rose against the whole basket, particularly the AUD (+5.8%). This led to FTSE, a foreign-dominated stock market, dropping about 1%.

Continue reading “April 2017: elections & returns” →

March ’17/Q1 progress: HMS Brexit launched

It’s the end of the month and the end of the quarter.  This is a combination post with my usual monthly portfolio performance along with a quarterly review of how I’m progressing on my goals for 2017.

What happened in March?  The UK saw its first terrorist outrage for years, with the disgusting car/knife attack at the Palace of Westminster.  While five people died (about the same as an average day of car fatalities, in fact), over 70 people were injured – which is thousands of people in families/friends affected.  It reminded me of the January Melbourne attack, in which a malcontent killed five people and injured 30 in a drug-fuelled car-only attack on the busiest street in the city centre.

Why in London there were twice as many people injured (or half as many people were killed, relative to total casualties), as in Melbourne I have no idea but would be interested if anybody has any insights.

What I can say is that I think London’s authorities/emergency services did an amazing job, with the criminal apprehended (erm, shot fatally) 80 seconds after the attack started, no collateral damage and lots of heart-warming stories of common sense, thinking under fire, charitable support and so on.

The other thought that will have occurred to lots of us is how thankful we Brits should be for our (almost) gun-free culture.  Extremists in the US do a lot more damage far more easily.

From an investment / UK markets perspective the big event was probably the UK government formally triggering Brexit via Article 50.  This event was so well choreographed that it had a negligible impact on the markets.  While I am no defender of the current UK government, in fairness to them they ended up implementing a Brexit process that they had laid out around six months ago, with zero amendments. They do deserve some credit for remaining in control and being true to their word.

By contrast, March also saw the UK’s first budget under the new(ish) regime.  This led to a farcical U-turn around National Insurance (the UK’s social charge, a.k.a. a tax on work). Unlike the Brexit saga this showed our senior leaders at their anti-leadership worst, in a petty dispute which did nobody any credit.  But nothing in the budget made any impact on markets /etc either.

Overseas, the main news in the markets was the defeat of Trump’s repeal of the Obamacare bill.  This wasn’t what pharma investors wanted.  But the wider impact is to call into question the Republican regime’s credibility, which in turn suggests they may not achieve the market-friendly changes to taxes and regulations that many hope for.

So in this environment, how did markets fare and how my portfolio perform?

Continue reading “March ’17/Q1 progress: HMS Brexit launched” →

My performance in Jan ’17 – Trumping begins

What a month.  First of all we get Theresa May’s Brexit 12 point plan, a.k.a. rebranding Great Britain as Global Britain (despite its lack of resonance with voters). Next we get the Trump inauguration.   Then we get Trump’s hyperactive first two weeks.  Never mind the hackneyed First 100 days of a new POTUS – Trump has done more damage to the USA’s overseas reputation less than 14 days into the job than Bush / Obama / etc managed in their first year.

Amidst all this the equity and bond markets have struggled to form a view.  USA equities are up a bit, UK bonds are down a bit, not much else to report.  Phew.

The USD has fallen a bit, thanks to concerted talking down by Trump and his putative administration.  They are accusing China of being a currency manipulator (which appears to be broadly true, albeit in the opposite direction to their claims), Germany of being an EU hegemon and currency abuser (for which there are quite good arguments, so I watch this meme with interest) and Mexico of, well, I’m not even going to go there.

For some reason the AUD has risen against the pound.  I’m not sure why. Combined with the USD fall this is quite a big shift in the terms of trade between Australia and the USA.

Continue reading “My performance in Jan ’17 – Trumping begins” →