My portfolio performance – September 2016. ‘Hard’ vs ‘soft’ Brexit emerges

September.  The academic new year.  The Jewish new year.  The end of the press silly season.  What did it hold for us?  More banging on about Brexit  – with the three Brexiteers all appearing to get slapped down by their boss at various points for saying we would / wouldn’t leave the single market / leave the customs union / trigger the legals by such-and-such.  Amidst the heat and the light, what actually happened?  Not a great deal.

The pound fell, of course, a bit further (though nothing compared to what, at the time of writing, the Tory party’s annual conference is doing to it).  This meant that UK equities were up. US equities were flat, remaining at record highs on some measures.  Bonds fell everywhere I track – by as much as 1.9% in the UK.  Does this mark the top of the bond cycle?  Time will tell, and time will also make a mockery of anybody who tries to make such calls.
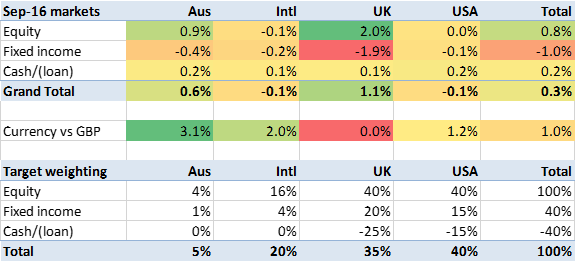
2016-09-returns-by-asset

Continue reading “My portfolio performance – September 2016. ‘Hard’ vs ‘soft’ Brexit emerges” →

My portfolio performance – August 2016 – interest rates cut to 0.25%

Wow.  August saw interest rates halve in the UK.  That isn’t something many of us are ever going to see again.  UK base rates are now 0.25%.  Some UK corporate clients are being charged for deposits.  Amazing times.

Of course UK bond prices, which inversely track interest rates (or, more precisely, expectations of interest rates) have risen.  Actually they haven’t risen by a striking amount – partly because expectations had been adjusting ever since the fateful day 23 June in which the UK very narrowly voted in favour of Brexit, whatever that means (it means Brexit – Ed.). SLXX, the iShares Corporate Bond ETF that I regard as a good proxy for UK bond prices, peaked at 156 in early August, up 20% from 130 in February.

In other news, UK equities rose a bit too.  Economic confidence seemed to be returning slowly to the UK, driven by a bunch of fact-free UK press reports that the economy is doing OK actually.  Overseas, markets were generally flat.  The pound actually rose very slightly against the three I track (USD, EUR and AUD).  The average market movement, weighted by my target allocation, was up 1.3%.  Not bad for a month, but relatively stable compared to recent increases.

2016-08-returns-by-asset

Continue reading “My portfolio performance – August 2016 – interest rates cut to 0.25%” →

My portfolio performance – July 2016 – new UK PM

The start of the month saw, pretty literally, anarchy in the UK.  By the end of the month the new Conservative government had made a decent fist of getting going, and Teresa May was starting to become a familiar face as the UK’s new head of government. Stability is returning, even if profound uncertainty regarding the Brexit implications remains.

From an investment point of view, measuring of course in pounds, it has been an amazing few weeks.

FTSE has risen above 6700.  A few weeks ago it fell below 6000.  If it manages that gain again it will be at an all-time record high. And the USA’s S&P reached new records, nearing 2200.

Bonds continued their relentless upwards march.  With interest rates seemingly staying lower than ever, and stability being prized, so bond prices are rising.  SLXX, the UK’s iShares Corporate Bond ETF, has risen from 130 in January to almost over 149 now – a rise of about 15% in six months.  Excluding coupon payments.  Astonishing.

And the pound, while much lower than pre-Brexit, has been relatively stable for a month.  It’s bounced between 1.29 and 1.33 to the US dollar.  In the context of its range of 1.37 to 1.58 in the previous 12 months, this is rock solid stable.

Continue reading “My portfolio performance – July 2016 – new UK PM” →