Finding ethical companies to invest in

I work for a company which takes pride in its ethics and values. So when I got chatting – as one does – with a younger colleague about pensions/investing recently she asked me how to invest in ethical stock market companies. As I’ve thought about this subsequently, I have realised what a minefield this topic is.

Let the ethical company cast the first stone

What’s unethical?  How about each of the following activities, for instance. Continue reading “Finding ethical companies to invest in”

Finally, I own a bit of Berkshire Hathaway

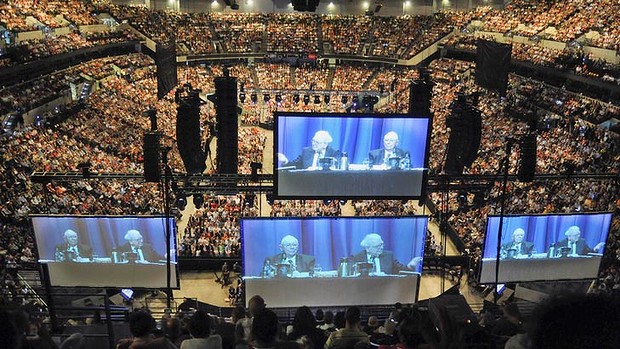
I have been a fan of Warren Buffett, the world’s biggest value-creator, since around 2000.  At the time I admired his past successes but assumed he would retire/die shortly and as a result never bought any of his stock.  But I’ve just bitten the bullet and bought a few shares of BRK.B, the ‘affordable’ mini share in his conglomerate, Berkshire Hathaway.

w-berkshire-hathaway-620x349

Having judged him too old to warrant a long-term investment, the more the years went past, the stronger this argument for not holding BRK became.  Why have I finally relented?  Two reasons:

  1. I would like an invite to the Berkshire Hathaway Annual General Meeting in Omaha.  The so-called ‘Woodstock for capitalists’ is on my bucket list so I hope to go before the great man himself kicks the bucket.
  2. Recent market dips make BRK appear to be OK value.  As far as I can work out BRK.B’s earnings per share are around $8.  This is a P/E of 16. This is a roughly market average P/E (and corresponds to an earnings yield of 6%) for a business with a very strong track record of delivering above-market EPS growth over a sustained time period.

Dodging an automotive bullet

I have been long on premium German carmakers for some time now, on the basis that a weakening Euro and a growing China would make premium European brands a good investment.  This makes the recent news of the VW scandal a fascinating moment for me.

volkswagen_logo_bleeding_by_greenbob1986

I’ve held BMW and Daimler (Mercedes), but not VW.  My omission of VW was deliberate; not because I think Golfs are less premium than 3-series and C-classes, but because I have never liked the shareholder governance at VW.

As soon as I read the VW news I sold my entire BMW and Daimler holdings.  This proved to be a timely call, because both stocks have fallen by over 10% since I sold.  I don’t normally sell holdings and I do still consider BMW and Daimler to be good long term bets.  But my gut told me that where there is smoke there is fire, and that the Germans hunt in packs, and whatever VW is being pilloried for is probably going to splatter its near rivals too.  So until the dust settles, I’m going to sit the sector out.

But the wider point here is my original decision to avoid VW.  I know it is too early to claim full vindication here (though I am certainly not the only investor to make this subjective call – VW’s has traded at a ~20% discount to less-premium Renault, for instance).  Why did I decide shareholder governance at VW wasn’t good enough for me?

There is a lot to like about VW.  It has large family holdings – which is usually good for a long-term outlook and dividend policies.  It has scale, and a pretty clear strategy.  It is ‘based in the right place’: Germany == Automobiles.

However, there are also some big red flags about VW: Continue reading “Dodging an automotive bullet”